What Does Pre-Approval Actually Mean (and Why Get It Before You Start Looking)?
If you've started looking into buying a house, you've probably run into two terms that sound almost identical: pre-qualification and pre-approval. A lot of people use them interchangeably. They're not the same thing, and the difference matters more than it sounds like it should.
Here's what each one actually means, and why getting the second one before you start touring homes in Topeka can save you a lot of wasted time.
Pre-Qualification Is an Estimate, Not a Commitment
Pre-qualification is usually quick and informal. You tell a lender roughly what you make, what you owe, and what you have in savings, and they give you a ballpark figure of what you might be able to borrow.
Nobody is checking your credit report line by line at this stage. Nobody is verifying your income with pay stubs or tax returns. It's a useful first gut check, but it's not something a seller can rely on, and honestly, it's not something you should rely on for your own budgeting either.
Pre-Approval Is the Real Thing
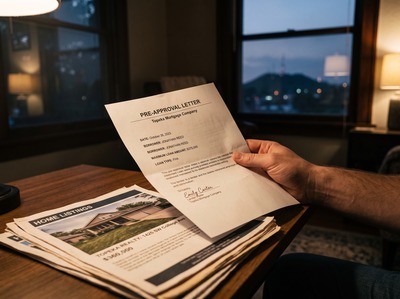
Pre-approval is a different level of scrutiny entirely. A lender pulls your actual credit report, verifies your income and employment, and looks at your real financial documents. At the end of that process, they give you a written letter stating how much they're willing to lend you.
That letter is what carries weight when you actually make an offer on a house. It tells the seller you're not just someone thinking about buying, you're someone a lender has already vetted and is ready to fund.
This process usually involves a general information conversation with a lender about your finances, not legal or tax advice. If you have questions about how a mortgage affects your specific tax situation or long-term finances, that's worth a conversation with an accountant or financial advisor alongside your lender.
Why This Distinction Actually Matters in Topeka
In a market like Topeka, where good homes in the right price range and neighborhoods can attract multiple offers, a pre-approval letter isn't just paperwork. It's often the difference between an offer that gets taken seriously and one that doesn't.
Put yourself in a seller's position for a second. If two buyers make similar offers on the same house, and one comes with a pre-approval letter while the other says they're "pretty sure" they'll qualify, which one would you trust more to actually close?
Sellers and their agents know the difference between pre-qualification and pre-approval, even when buyers don't. Showing up with real pre-approval in hand signals that you've done your homework, and it can make your offer meaningfully more competitive without you having to offer a higher price to compensate.
What Pre-Approval Doesn't Guarantee
It's worth being clear about what pre-approval is and isn't. A pre-approval letter is not a final loan commitment. Your lender will still need to verify details about the specific house you're buying, including an appraisal, and your financial situation needs to stay roughly the same between pre-approval and closing.
Taking on new debt, changing jobs, or making large unexplained deposits into your bank account during this window can all complicate things. This is general information, not a complete list, and every lender's process varies slightly, so ask your specific lender what to avoid once you're pre-approved.
When to Get Pre-Approved
The short answer: before you start seriously touring homes, not after you've found one you love.
Getting pre-approved early gives you an honest number to search within, so you're not wasting time looking at houses above or below what actually makes sense for your budget. It also means that when you do find the right house, you're ready to move quickly, which matters in a competitive market.
Where an Agent Fits Into This
A good buyer's agent won't replace your lender, but they usually work closely with one, and they can help you understand how your pre-approval amount translates into a realistic search range once taxes, insurance, and other costs are factored in.
Team Ringgold works with buyers across Topeka and Shawnee County at exactly this stage, helping people connect with lenders and understand what their pre-approval number actually means for their house search. If you're not sure where to start on the lending side, that's a good first conversation to have.
Reach out to Team Ringgold any time if you want to talk through where you stand before you start looking. No pressure, just a straight answer.