Home Buying Tips
By John Ringgold, Team Ringgold at Keller Williams | July 24, 2026
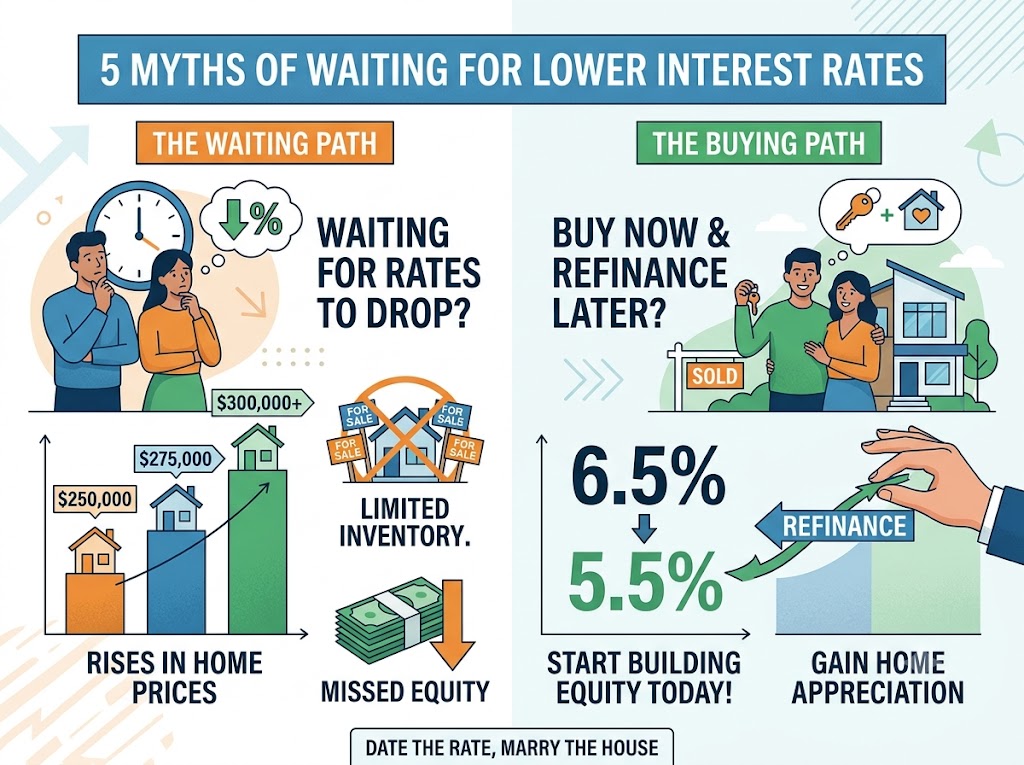
If you're thinking about buying a home in Topeka, chances are you've had this thought: "I'll just wait until interest rates come down." It sounds reasonable. But for most buyers, waiting has actually cost more money than buying sooner would have. Home prices have risen for 34 consecutive months nationally, inventory remains tight, and nobody has a crystal ball on rates. Below, we walk through five of the most common myths about waiting for interest rates to drop — and the real data behind each one.
Myth #1
"Rates are about to come down, so I should wait."
The Fact
Nobody can reliably time the mortgage market — and the cost of waiting is real.
Rates have been "about to drop" for years, and buyers who kept waiting kept getting burned. Right now the 30-year fixed is sitting at 6.58% (Freddie Mac, July 23, 2026). Even the economists who do this for a living have been wrong repeatedly about when and how fast rates would fall. The problem with waiting is that it's not free. Every month you rent instead of own is a month you're paying someone else's mortgage instead of your own. No equity building, no appreciation working in your favor, no tax deduction. A buyer who bought a $250,000 home two years ago has likely built tens of thousands in equity by now. A buyer who waited is still waiting, and that gap keeps growing.
Myth #2
"When rates drop, I'll be able to afford more house."
The Fact
Lower rates flood the market with buyers, which drives prices up and cancels out the savings.
Think of it this way: if rates drop to 5.5%, every buyer who was sitting on the sidelines jumps back in at the same time. That's a flood of new competition chasing the same limited number of homes. When demand spikes and supply stays tight, sellers raise their prices — and they can. Your monthly payment might look a little better on paper, but the purchase price goes up to offset it. History backs this up. When rates dropped in the early 2000s, home prices surged. When they hit historic lows in 2021, prices went completely haywire. Lower rates feel like a win until you realize everyone else got the same memo and the house that cost $300,000 today is now listed at $330,000.
34
Consecutive months of rising home prices nationally through April 2026
Source: Better.com / NAR
Myth #3
"There will be more homes to choose from if I wait."
The Fact
Inventory is declining again in 2026 — and the core reason isn't going away anytime soon.
Here's the core problem: about 60% of homeowners have a mortgage rate below 4%. They bought or refinanced when rates were at historic lows, and they are not giving that up to move into a 6.5% loan. So even if they'd love a bigger house, a different neighborhood, or something closer to work, they're staying put. That means the homes just aren't coming to market the way they used to. Nationally, inventory is still about 17% below pre-pandemic levels, and as of mid-2026, inventory growth has actually turned negative year-over-year in several markets. Waiting for more choices could mean waiting for a problem that isn't going away anytime soon, because the incentive for those locked-in sellers to move simply doesn't exist at current rates.
Myth #4
"Home prices will drop too, so waiting wins twice."
The Fact
Home prices have risen for 34 straight months. The "double win" hasn't materialized for anyone who's been waiting.
This is probably the most expensive myth of all. Prices haven't dropped. The national median existing-home sale price hit $429,300 in May 2026, and here in the Midwest we're up over 3.6% from last year. That's on top of the gains from the year before. Buyers who decided two years ago to wait for prices to fall paid more when they finally bought, not less — and they missed out on all the appreciation in between. Unless there's a major economic shift that forces widespread selling, the supply shortage is what's holding prices up, and that shortage isn't going anywhere fast. Hoping for a price correction while inventory stays this tight is a bet that hasn't paid off in three years running.
Myth #5
"If I buy now and rates drop later, I'm stuck with this rate forever."
The Fact
You can always refinance. You can't go back in time and buy at today's price.
Refinancing is a real, straightforward option. If rates drop to 5.5% next year, you call your lender, start the process, and in a few weeks you have a lower payment. It's not complicated and people do it all the time. But here's what you can't do: go back in time and buy a house at this year's price. The home you could buy at $285,000 today might be $300,000 or $310,000 by the time rates drop enough to feel worth waiting for. And in the meantime, you've paid rent, missed months of equity growth, and missed the appreciation. The old saying in real estate is "date the rate, marry the house" — and it holds up. Lock in the asset now, and when rates give you an opening, take it.
Ready to Stop Waiting and Start Building Equity?
If you're thinking about buying a home in the Topeka area, let's talk through your options. No pressure, no obligation — just a straight conversation about what makes sense for your situation right now.
Talk to Team RinggoldSources
- Mortgage Rates Today, July 24, 2026 — Yahoo Finance
- Freddie Mac 30-Year Rate, Week of July 23, 2026 — Fortune
- 34 Consecutive Months of Rising Prices — Better.com
- FHFA House Price Index Q1 2026 — Federal Housing Finance Agency
- Why Housing Inventory Growth Is Slowing in 2026 — HousingWire
- Historical Mortgage Rate Trends — Bankrate