Closing costs for a Topeka home buyer often run roughly 2% to 5% of the purchase price. Your lender's loan estimate shows your real number, and the title company confirms the exact amount a few days before closing.

Yes, you can buy a home in Topeka with little or no money down. Get our free guide to FHA, VA and USDA loans and the 7 steps from pre-approval to closing.
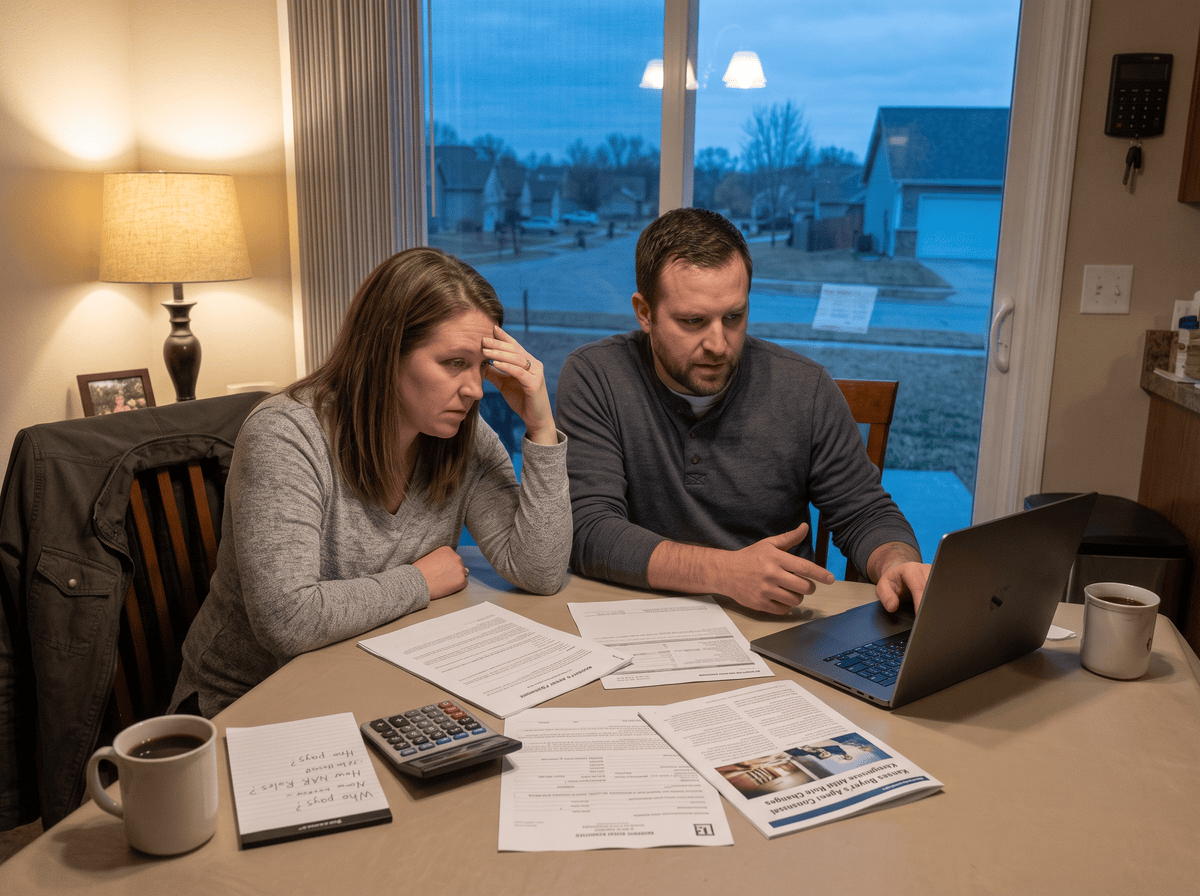
If you've searched "who pays the buyer's agent" lately, you're not alone. Real estate commissions changed nationwide in 2024, and a lot of the old assumptions buyers and sellers used to rely on don't automatically apply anymore. Here in Topeka and Shawnee County, we're fielding this question from both sides of the table almost every week.
Shopping before you know your credit and budget is one of the costliest mistakes a Topeka buyer can make. Get our free guide to all 11 buying mistakes to avoid, in the order you'll run into them.
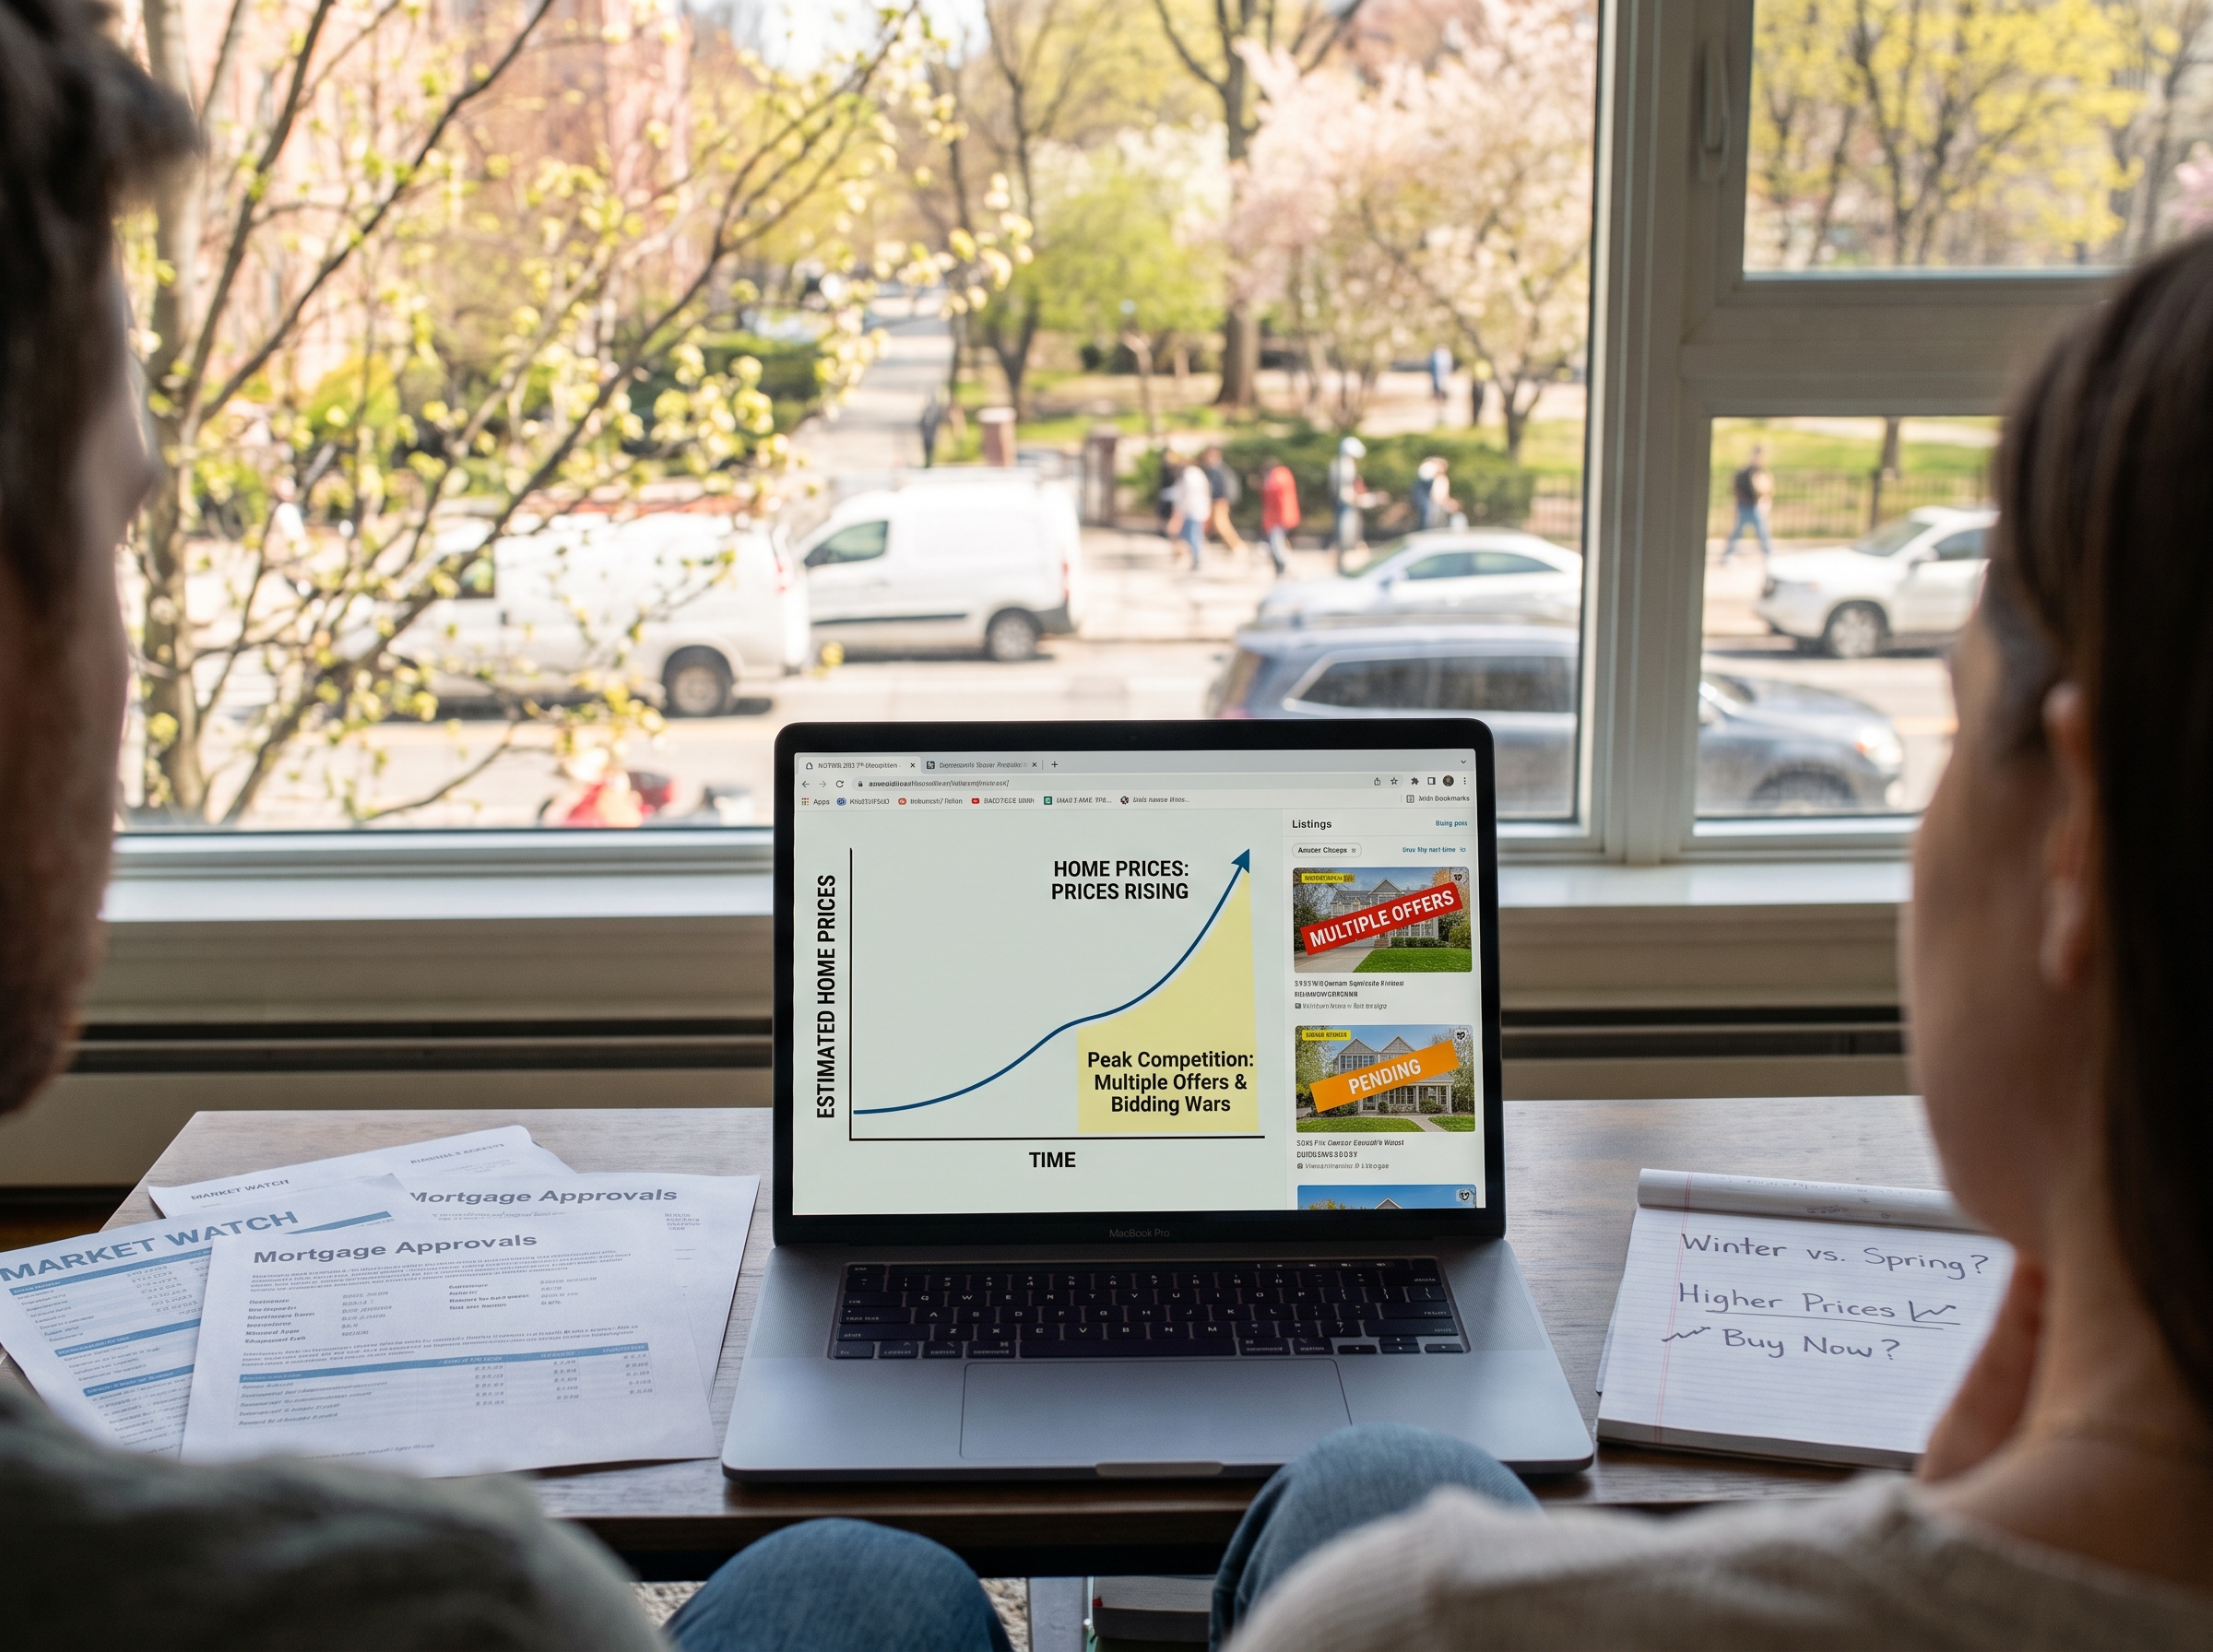
Should you wait until spring to buy a home in Topeka? For many buyers, waiting means shopping at the busiest time of the year. Shawnee County sales data shows more homes selling, and selling faster, in the spring than in the fall. Here’s what that means for you.

The first 5 steps to buying a house in Topeka are to check your finances, get pre-approved, find a local agent, search within your real budget, and make an offer backed by real numbers, in that order. Skipping ahead is where most buyers get stuck.

Down payment assistance is extra money, usually a second loan or a grant, that helps Topeka buyers cover their down payment and closing costs so they don't need as much cash saved up front.
Pre-qualification is a quick, informal estimate of what you might be able to borrow. Pre-approval is a lender's written statement of how much they're willing to lend you, based on your verified credit and income, and it's the one that carries weight when you make an offer on a house in Topeka.

Planning to Buy a Home Next Spring? Here's Why Fall Is When the Real Work Starts
If you're picturing yourself moving into a new home in Topeka next spring, it's tempting to think you've got plenty of time. Spring feels far away in September.
It isn't, though. Not for the parts of buying a home that actually take time to fix.
Your credit score and your down payment aren't things you can improve overnight. They respond to months of steady habits, not a few weeks of scrambling right before you want to make an offer. If spring is your real target, fall is when the groundwork needs to start.
Why Credit Takes Months, Not Weeks
A lot of buyers assume credit is something you check once, right before you talk to a lender. In reality, your score is a rolling average of your financial behavior, and it moves slowly by design.
Paying off a credit card balance today doesn't instantly erase months of high utilization. Disputing an error on your report can take 30 to 45 days to resolve, sometimes longer. And if you have any late payments or collections to work through, rebuilding a track record of on-time payments simply takes time passing, not a clever trick.
That's the whole case for starting now. Give yourself six months instead of six weeks, and you have room for your actual habits to show up on paper before a lender ever pulls your file.
Start With Your Credit Report, Not Your Score
Before you worry about raising a number, find out what's actually on your credit report. You're entitled to a free copy from each of the three major bureaus once a year at annualcreditreport.com, which is the only site required by federal law to provide the free version.
Go through it line by line and look for:
- Accounts you don't recognize, which could signal an error or identity theft
- Old debts that should have fallen off but haven't
- Balances that are higher than what you remember
- Late payments, especially anything recent
If you find something wrong, dispute it directly with the bureau reporting it. Errors get fixed more often than people expect, but only if someone actually flags them.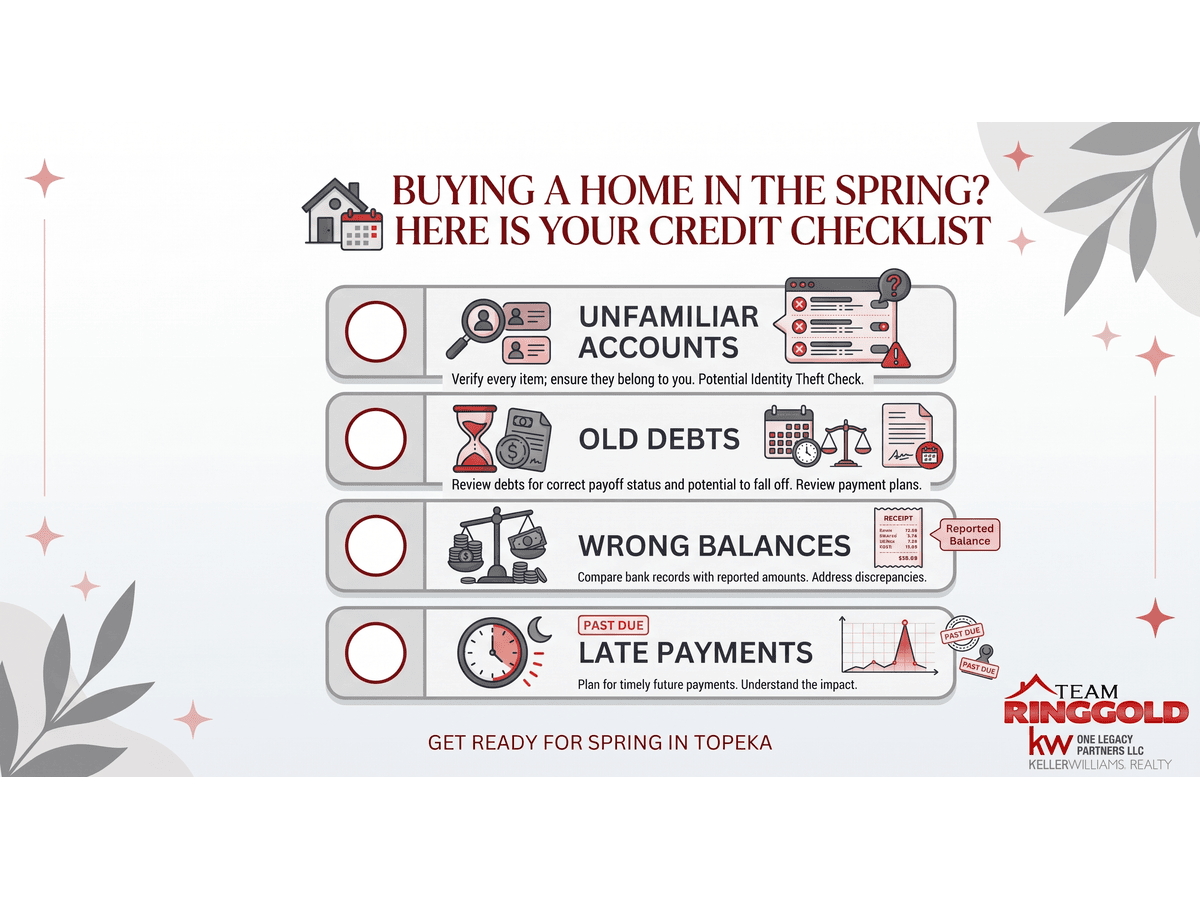
The Habits That Move Your Score Between Now and Spring
Once you know what your report actually says, a handful of habits do most of the real work over the next several months.
Pay every bill on time, every time. Payment history is the single biggest factor in most credit scoring models. One missed payment can undo months of otherwise good progress, so this is the habit worth protecting above all others.
Bring down your credit card balances. Credit utilization, how much of your available credit you're actually using, matters more than most people realize. Getting balances down, even before you pay them off completely, tends to move your score faster than almost anything else you can do.
Don't open new credit accounts right now. That new store card with 20 percent off your purchase, or the offer for a new car loan, both trigger a hard inquiry and a new account, which can temporarily lower your score right when you don't want it to move. Save the shopping spree for after closing.
Don't close old accounts either. It feels like tidying up, but closing a long-held card can shorten your average credit history and reduce your available credit at the same time, both of which can work against you.
For a closer look at what's on your credit report and how scoring actually works, see our credit score guide.
Building Your Down Payment on a Fall-to-Spring Timeline
Credit and down payment savings run on parallel tracks, and fall gives you the same runway advantage for both.
A few practical moves that work well on a six-month timeline:
- Open a dedicated savings account just for the down payment, separate from your everyday checking, so it's harder to dip into without noticing
- Set up an automatic transfer on payday, even a modest one, so saving happens before you have a chance to spend it
- Take a hard look at recurring subscriptions and expenses you can pause for a few months
- If a holiday bonus or tax refund is coming, decide now that it's earmarked for the house fund before it lands in your account
It's also worth asking a lender about down payment assistance programs available to Kansas buyers. Eligibility and terms shift depending on the program and your specific situation, so this is general information rather than a guarantee, and a loan officer can tell you what you actually qualify for.
Why Lenders Care About Both Numbers Together
Your credit score and your down payment aren't evaluated separately. A lender looks at the whole picture, including your score, your available cash, and your debt-to-income ratio, to decide not just whether you qualify for a loan, but what interest rate and terms you'll actually get offered.
A stronger credit score paired with a solid down payment can mean a meaningfully better rate over the life of the loan. That's a general lending principle, not a promise about your specific numbers, and the details depend on the lender and the loan program. A conversation with a local lender now, even before you're ready to buy, can tell you exactly where you stand and what would move the needle most for your situation.
What This Looks Like on a Calendar
If spring is the goal, a rough six-month runway starting now might look like this:
- Now through October: Pull your credit reports, dispute any errors, and open a dedicated savings account
- November and December: Keep balances low, pay everything on time, automate your savings, and resist new credit accounts through the holidays
- January and February: Talk to a lender about pre-approval and see where your score and savings actually stand. This is also a good time to learn the difference between pre-qualification and pre-approval
- March and beyond: Start the active home search once you know your real numbers
None of this has to be perfect. The point isn't hitting an exact score or an exact savings figure by a specific date. It's giving your habits enough time to actually show up in your financial picture before you need them to.
Where Team Ringgold Fits In
None of this replaces a conversation with a lender, who can look at your actual numbers and tell you where you stand. But once you've got a handle on your credit and your savings, an agent who works with Topeka buyers regularly can help you figure out what that translates to in terms of neighborhoods, price ranges,
2655 SW Wanamaker Rd
Topeka, KS 66614
🥫🍝🥜🌽
Fall Food Drive!
Help us fill the shelves this season!
Every item you give helps put a meal on the table for a neighbor in need.
🎯 Our Goal: Stock the Topeka Rescue Mission with meals for those in need
🥫 What We Need: Non-perishable food: canned goods, pasta, rice, cereal, peanut butter
🤝 How You Can Help: Pledge your donation today!